The ammonia age: How Europe and Africa can steer global shipping to net zero

Summary
- The International Maritime Organisation’s Net-Zero Framework offers the most effective path to decarbonise global shipping.
- The Net-Zero Framework would establish uniform global emissions rules, levelling the playing field for regions like the EU where carbon pricing already applies, supporting European industrial competitiveness and resilience.
- Adoption of the framework could unlock demand and investment for green-hydrogen-based fuels, the most viable green fuels suitable for long-distance shipping, helping to scale production and lower costs.
- The shipping industry broadly supports the Net-Zero Framework, but divisions among the International Maritime Organisation’s members have stalled progress; pressure from the US and major oil producers has undermined consensus.
- Without the framework, a patchwork of regional decarbonisation schemes will emerge, increasing compliance costs, encouraging regulatory arbitrage and slowing the development of green fuels.
- African countries could be decisive in the upcoming International Maritime Organisation vote. Securing their support will require credible European commitment to regulatory clarity, joint development of green fuels and collaboration to ensure Africa’s maritime sectors are not left behind in decarbonisation.
The battle over clean shipping
The need to decarbonise global shipping is no longer in doubt. How to do so remains fiercely contested. The sector contributes almost 3% of global greenhouse gas (GHG) emissions today, projected to reach 10% in 2050. Yet it remains one of the hardest sectors to clean up. New low-carbon fuels need to be developed, vessels retrofitted, equipment and infrastructure upgraded. These costs create a “transition premium”, compounded by a persistent “green premium” as low-emission fuels remain much more expensive than conventional ones. These higher costs, together with resistance from fossil fuel producers, have slowed progress.
The stakes extend beyond climate. Shipping carries more than 80% of global trade by volume and is deeply exposed to energy market volatility. Oil and gas supply is geographically concentrated and vulnerable to disruption. The ongoing conflict around the Strait of Hormuz is a case in point: it has driven oil prices and maritime insurance costs up sharply, and disrupted oil and gas production and distribution in the region, with significant global impacts. Even if the war ends within weeks, damage to energy infrastructure will take years to repair.
A decarbonising shipping industry drawing on more diverse energy sources, including green fuels with more geographically dispersed production, would be more resilient, both for shipping itself and the industrial sectors that depend on it. Extending emissions pricing to all international shipping is also key to levelling the playing field for operators based in jurisdictions where emissions pricing is already in force, helping protect the competitiveness of their industries by levelling trade costs.
The International Maritime Organisation (IMO), the UN entity tasked with regulating the global shipping industry, has set out a pathway aligned with these goals. In recent years, the organisation has made steady progress. In 2023, members unanimously approved the updated GHG strategy to reduce emissions by 20-30% by 2030 and 70-80% by 2040 (from 2008 levels). In April 2025, the IMO’s environmental body approved a draft Net-Zero Framework (NZF) to implement the agreed GHG targets.
This cleared the way for the final adoption of the NZF at the IMO’s Extraordinary Session in October 2025. Despite strong momentum, several influential countries, chief among them the US and Saudi Arabia, reportedly derailed the planned vote and intimidated other states to oppose it.[1] Faced with evidently divided positions, members opted to postpone the vote for 12 months. What was largely a technical process became entangled in geopolitics.
The NZF is now heading for a decision in December 2026. The delay could harden opposition or help clarify provisions and build support. Much hinges on the EU, the NZF’s main backer, and its ability to win over African countries, which could swing the vote if they act in concert. Obtaining their buy-in will require a strong partnership offer from Europe that outweighs the coercion from the US and the Gulf.
This policy brief argues that Africa and Europe should act together to secure adoption of the NZF and sets out how Europe can bring Africans on board. There is considerable scope for cooperation. For African countries, the NZF opens the prospect of developing new green-fuel industries rather than only occasioning the costs of transition. Green hydrogen-based fuels, notably green ammonia and green methanol, present the most promising fuels to drive maritime decarbonisation. The NZF could act as a market catalyst, providing predictable demand that will help scale production and reduce costs over time.
The alternative to the NZF is not the status quo. In the absence of a global framework, a patchwork of national and regional emissions schemes will proliferate, duplicating compliance burdens and distorting what is inherently a globally interlinked industry. The question is no longer whether shipping will be priced for its emissions, but how. A global framework that pushes a standardised approach; fuel switching rather than mere emissions trading; and economic mitigation for developing countries offers the best chance for an equitable transition.
The NZF and its contenders
The framework’s novel mechanisms
The NZF would apply to ships of 5,000 gross tonnage and above engaged in international trade. It combines binding emissions targets with a pricing mechanism for non-compliance. At its core are two elements.
First, introducing a global fuel standard that requires ships to, over time, reduce their annual GHG fuel intensity (GFI), defined as the quantity of GHG emitted per unit of energy consumed. Second, the NZF would also see adoption of a global economic measure, whereby ships exceeding the annual GFI limit must offset excess emissions by acquiring remedial units. These could be drawn from previously banked units, purchased from other ships or obtained through contributions made to the IMO Net-Zero Fund (more information below). Ships that outperform the standard could bank their surplus units (for up to two reporting periods), sell them to other ships or voluntarily cancel them. Additional financial rewards are available for ships using zero or near-zero emission fuels.
Unlike other proposed decarbonisation frameworks, the NZF envisions a two-tier compliance system, with different penalty levels serving different purposes:
- Tier 2 (Base compliance): Applies to higher emitting ships, or those that exceed the Tier 1 threshold. These ships must purchase remedial units at $380 per tonne of carbon dioxide. The goal is to discourage use of high-emission fuels and drive switching to low-emission alternatives.
- Tier 1 (Direct compliance): Applies to ships with lower emissions that still exceed targets. These ships must purchase remedial units at $100 per tonne of carbon dioxide. This penalty is lower than abating options under most emissions-trading schemes and is designed to generate a predictable revenue stream for the Net-Zero Fund.

Both base and direct compliance targets become stricter over time. As a result, a ship that exceeds Tier 1 today would exceed Tier 2 within a few years with the same level of emissions. The escalating cost for non-compliance pushes ships to switch to lower-emission fuels rather than merely continuing to offset excess emissions through remedial units, which reallocates units but does not overall lower emissions. The $380 and $100 per tonne penalties would apply for the period between 2028 and 2030, with future pricing to be reviewed periodically.
The Net-Zero Fund is another novel feature of the NZF. It channels Tier 1 penalty revenues to support developing countries to transition their shipping industries. This includes support for innovation, research, infrastructure, just transition initiatives, training, technology transfer, capacity building and mitigating negative impacts on vulnerable states. Its effectiveness requires stable and predictable revenues, making the combination of the two-tier approach and Net-Zero Fund critical components of the NZF.
Other maritime decarbonisation efforts
Although the IMO’s NZF is currently garnering the most attention, it is not the only decarbonisation framework applying to shipping. The EU has had an Emissions Trading System (ETS) Directive in force for the maritime sector since 2024, requiring ships docking at EU ports to report their emissions and purchase credits for voyages into and out of those ports. The EU also enacted the FuelEU Maritime Regulation, which sets progressively stricter limits on emissions for commercial ships of 5,000 gross tonnage and above, targeting a 59% reduction by 2045. Britain has an ETS that will be extended to include shipping as of July 1st 2026, while Japan and Canada have also proposed emissions pricing schemes. Various other regions and countries also intend to introduce pricing schemes for maritime emissions should the NZF adoption fail in December 2026.
Some alternate global systems have also been proposed. A group of Pacific Island states has put forward the Global GHG Fuel Standard and Global GHG Levy, pairing a fuel standard with an emissions pricing mechanism, but without an emissions trading component. China has also proposed an alternative system, the International Maritime Sustainable Fuels and Fund (IMSF&F), which has garnered support from Brazil, Saudi Arabia, South Africa and others. It mirrors the Tier 2 (Base) scenario of the NZF, combining a fuel standard and a compliance market for emissions trading. However, because it envisages a less steep decarbonisation trajectory, it is seen as friendlier to oil producers and developing countries. But, in lacking an equivalent to the Tier 1 (Direct compliance) mechanism, it would not generate the stable and predictable revenues needed to support a comparable transition fund.
This landscape of proliferating maritime emissions pricing schemes demonstrates a clear trajectory towards decarbonising the shipping industry, one way or another. But will it occur under a globally uniform framework that supports a more equitable transition? Or through a fragmented set of frameworks that risk duplicating compliance costs and creating scope for regulatory arbitrage with little targeted support for developing countries?
The NZF and its discontents
It is useful to understand the geopolitical manoeuvring at the October 2025 IMO Extraordinary Session, as these dynamics are likely to continue into the December 2026 re-consideration of the NZF adoption.
Only countries that have ratified the International Convention for the Prevention of Pollution from Ships (MARPOL) Annex VI are eligible to vote on the NZF. This group comprised the vast majority of countries present at the October 2025 meeting, but several non-eligible IMO members were also present. Since it ended up being a poll for or against postponement rather than adoption of the NZF, all countries present were allowed to vote.

Countries that voted against postponement were effectively backing the adoption of the NZF and did not want a delay to disrupt the process. Europeans accounted for over half of this group’s votes, following by Pacific Island countries—even leading flag-of-convenience countries (which allow, for a fee, ships to use their flag despite actual ship ownership sitting elsewhere), such as Palau and the Marshall Islands. This demonstrates a clear, coordinated position by Pacific Island nations, which face a disproportionate impact from climate change and for which curbing emissions is a matter of survival.
Support for postponement came from a more heterogenous group. While certain countries outright oppose NZF adoption, it seemed others have concerns about specific provisions. Some voted for a delay in order to gain more clarity from the NZF’s guidelines, which are intended to provide more detail on the regulation’s provisions. And others appear to have been intimidated into voting for postponement.[2]
Oil-producing countries dominated support for postponement. Major Gulf producers, particularly Saudi Arabia, reportedly strongly opposed the NZF and dissuaded others from supporting it.[3] Although many oil and gas producers globally are working to diversify their economies, the NZF’s steep decarbonisation trajectory threatens their earnings and economic stability and, for some, also their geopolitical standing.
The US has also emerged as a strong opponent of the NZF since the start of President Donald Trump’s second term. Reportedly, America also applied direct pressure on other countries to align with its stance, including threats of sanctions and trade reprisals.[4] Kenya, which vocally champions green initiatives and was supportive of NZF adoption in April 2025, switched to favour postponement after reportedly being directly targeted by the US.[5] Even where pressure was less explicit, many African governments may have been wary of displeasing Gulf nations, which provide increasingly important sources of investment, or incurring the wrath of America’s mercurial president, who had already levied trade tariffs of 10-50% on many of them at the time of the vote. As an African expert described, “It was very obvious that the US was threatening others. They really brought influence to bear on as many states as they could.”[6]
After oil producers, African countries were the next sizeable contingent in favour of postponement. Notably, 11 of the 25 African countries present were not eligible to vote on NZF adoption as they have not ratified MARPOL Annex VI. Faced with a procedural poll, seven of these non-eligible countries voted to postpone while the remaining four abstained. Half of this non-eligible group are fossil fuel producers, but as these countries had not come to the meeting expecting to vote, they could have opted for postponement—either to buy time to clarify NZF guidelines, or because they succumbed to threats from NZF opponents.
African countries had little opportunity to coordinate ahead. They met as a group for the first time only the day before the vote, leaving little time to reconcile divergences. The fractured African position is symptomatic of a broader dynamic: the breakdown of a global order that previously provided certainty to international trade and maritime cooperation. African countries are navigating new waters characterised by more transactional engagements that are often far more unpredictable and conditional than in the past. As acknowledged by Ali Mohammed, Kenya’s special envoy on climate change, “We are all witnessing that international negotiations are no longer shaped by technical considerations alone. They are influenced sometimes quietly, sometimes openly, by power dynamics, strategic interests and economic leverage.” He added that the lack of consensus seen during the October 2025 IMO meeting is emblematic of “The diversity of national circumstances and economic structures, including those within Africa itself.”
Varied voting patterns were seen among large merchant shipping and flag-of-convenience states. Half of the countries with large merchant fleets voted against postponement, indicating support for the NZF. Even more surprising was that the majority of flag-of-convenience countries either voted against postponement or abstained. These countries benefit specifically from being able to exploit regulatory arbitrage by offering ships more lax rules than elsewhere, so support from a number of them for NZF adoption (which would impose a globally applied framework) is particularly surprising and welcome.
This group also demonstrated clear shifts from earlier positions, reportedly due to the pressure from the US[7] and, presumably, the Gulf states. Flag-of-convenience countries Bahamas and Liberia, for example, had been active supporters of the NZF in April 2025 but voted for postponement in October. Greece and Cyprus, EU members with large merchant fleets, were in favour of NZF adoption in April 2025 but abstained in October—the only EU states not to oppose delay. Among major Asian economies, China, India, Japan and South Korea all changed their vote from the April meeting, with the first two voting to postpone and the latter two abstaining.
Several clear conclusions can be drawn from the tumult of the October 2025 meeting. First, America’s disengagement from climate action created space for oil producers to derail the NZF. Second, in a context where the vote of every country carries equal weight, African countries could have swayed the outcome had they coordinated. Third, some countries have legitimate concerns about maritime decarbonisation and the NZF text as it stood in October 2025. The EU will have to address these concerns if it wants to secure adoption in 2026.
What is dissuading NZF support
Decarbonising shipping is widely seen as necessary, both from a climate and regulatory uniformity perspective. The shipping industry itself largely accepts this. However, the pace and trajectory of decarbonisation remain contested.
In addition to higher costs of low-emission fuels, switching fuels is also expensive. Existing fleets and port infrastructure need to be retrofitted, new supply chains and associated infrastructure developed, and seafarers trained to use new fuels and technologies. The requirements vary by fuel type and can be significant. Against this backdrop, criticism of the NZF tends to fall into two categories: concerns with the NZF’s design, and availability and price of low-emission alternative fuels.
Concerns with the design
The NZF’s decarbonisation trajectory is seen as too steep for oil producers. As the text currently stands, liquified natural gas (LNG) could become non-compliant in as little as five years.[8] For economies still heavily reliant on fossil fuels, such a short timeline is difficult to absorb. It also sits uneasily with the current state of green-hydrogen production—limited supply risks driving prices above their already high production costs. A more gradual trajectory would better align with economic adjustment for fossil fuel producers and with scaling green-hydrogen production; but too gradual a trajectory incurs considerable emissions that could be avoided on a shorter timeline and lowers the NZF’s effectiveness.
A second concern is regulatory overlap, notably with the EU’s ETS and FuelEU Maritime Regulation. A firm commitment is needed from the EU that it will withdraw these mechanisms from international shipping should the NZF be adopted and maintain them for shipping within Europe only. Ahead of the October 2025 vote, the EU indicated that it would “review relevant regulation” after adoption of the NZF, falling short of providing a firm commitment. Additionally, during NZF negotiations, EU member states reportedly opposed a UAE-led proposal to recognise the NZF as the “only” global maritime decarbonisation regulation, preferring that it instead be recognised as the “primary” one. Considering that NZF adoption will already incur costs for shipowners and raise trade costs, particularly in developing countries, the choice of words is not trivial here.[9] “No one wants to see NZF in addition to the EU’s ETS for shipping. That was a total red line for many African states,” explained an African observer of the process.[10]
Availability and price of low-emission fuels
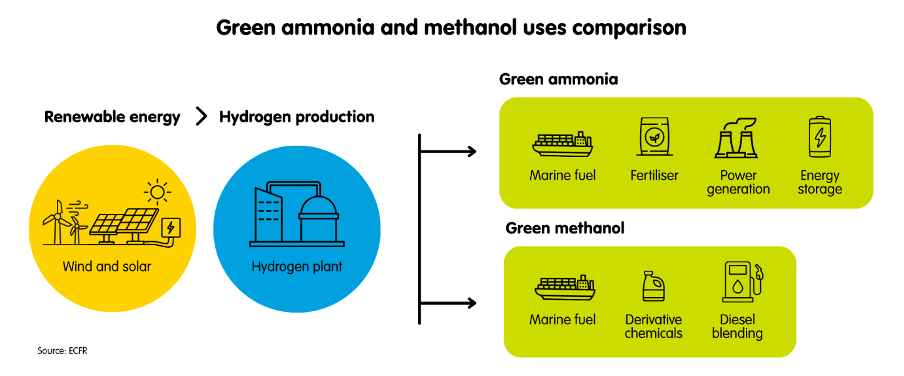
The cost and availability of alternative fuels is another key challenge. Green ammonia and green methanol, the most promising low-emission fuels appropriate for long-distance shipping, are derivatives of green hydrogen, which is produced from water via electrolysis using renewable energy. Neither is produced today at competitive prices or at sufficient scale to meet the needs of the shipping industry.
This creates a paradox. Compliance with the NZF depends on these fuels, but their large-scale deployment may depend on the NZF. By creating predictable demand, the framework could be the jump start needed to unlock investment, scale up production and start bringing down costs.
Green hydrogen has gained some momentum over the last decade. Major economies including China, the EU, India, Saudi Arabia and the UAE have incorporated green hydrogen into their transition roadmaps. Yet stubbornly high costs have tempered enthusiasm, particularly in Europe. Projects have stalled or been postponed.[11] In June 2025, ArcelorMittal, Germany’s leading steelmaker, reportedly abandoned plans to convert two of its steel plants to green hydrogen, while Thyssenkrupp, another major German steelmaker, indicated that it may need to run its planned flagship green facility on fossil fuels unless the cost of green hydrogen comes down.
Meanwhile, China is far and away the global green hydrogen leader, now holding 50% of global production capacity, which is still only around 125,000 tonnes per year. India’s production is more nascent but is set to expand significantly in coming years, with the country having set a target of producing five million tonnes annually by 2030. The vertically integrated structure of large companies in both countries could be a key factor in improving cost competitiveness.[12]
The economics of green hydrogen
Green hydrogen struggles to compete against conventional fossil fuels as well as other forms of hydrogen: grey hydrogen, which is produced using fossil fuels (usually natural gas or coal), and blue hydrogen produced using natural gas with (incomplete) carbon capture and storage. Green hydrogen remains more expensive than these conventional alternatives. In 2025, it was priced at $2.28-7.39/kg compared to $0.67-1.31/kg for grey hydrogen. This is a substantially higher cost, particularly if grey hydrogen’s carbon emissions are not priced in. However, green hydrogen is becoming increasingly cost competitive with blue hydrogen, which was priced at around $2.00-3.50/kg in early 2026. Although portrayed as a lower-emission option, in practice most blue hydrogen projects capture less than half of the carbon they produce. Higher capture rates are technically possible but raise production costs.
Demand has been equally weak. Consumers in developed markets are reluctant to pay what is essentially a premium for green hydrogen. European buyers have been wary to commit to offtake agreements without price certainty.[13] But without committed offtake, projects cannot secure investment or provide price certainty until they are in production. It is a classic chicken-and-egg dilemma: high costs keep demand low, and low demand keeps costs high.
There are signs this could shift. Prices of solar panels, energy storage batteries and wind turbine technologies are declining. Electrolysers, currently priced between $1,000-$1,500 per kW, are expected to fall below $400 per kW in the next 10-15 years. Higher oil and gas prices, driven in part by the Iran conflict, are also narrowing the gap.
Two conditions are necessary for scaling the green hydrogen sector. First, effective global carbon pricing on emissions from fossil fuels, to level the playing field between green and fossil fuels and across countries and regions. Second, significant and predictable demand, which the NZF could unlock.
This creates a tension between Europe’s supportive stance on NZF adoption and its scepticism around green hydrogen. In practice, the two are inseparable, as today green hydrogen’s derivatives green ammonia and green methanol are the leading options for low-emissions fuel for the shipping industry. Should the NZF be adopted, compliance will not be possible without green hydrogen derivatives.
Alternative low-emission fuels for shipping
Between green ammonia and green methanol, there is not yet a clear winner for a zero or near-zero emissions alternative to oil and LNG to power the shipping industry. It is most likely that a combination will be used. As explained by a representative of Maersk, the Danish shipping giant, “No single fuel is likely to meet the diverse needs of global shipping, given differences in vessel types, routes, infrastructure availability and regulatory frameworks.” There may also be a time dimension, whereby some fuel options are more feasible in the short term while others offer greater sustainability in the longer term.
Some experts favour green ammonia as the best long-term option. It contains no molecular carbon, so produces no carbon emissions. It has a competitive energy density and possibly greater potential for scalability than methanol. However, it is unstable and flammable, requiring more safeguards, including specialised storage on ships and at ports, as well as careful handling during refuelling. It can also be toxic if it leaks, potentially releasing nitrogen oxides (a pollutant that causes respiratory problems) and nitrous oxide (a strong greenhouse gas). While its production costs are slightly lower than those of methanol, it would require higher costs to modify ships and port infrastructure.
Methanol, on the other hand, is relatively more costly to produce but requires fewer modifications to port infrastructure, bunkering and storage facilities than ammonia. Methanol is safer and easier to handle, and more compatible with existing engines—but, as with LNG, vessels would need double-walled fuel distribution systems for security. It does contain molecular carbon, although it emits significantly less carbon than conventional fuels.
Shipping companies have different preferences on which fuel to adopt. France’s CMA CGM, Denmark’s Maersk and China’s COSCO are purchasing dual-fuel ships that can operate using green methanol as well as conventional fuels, while Swiss MSC is equipping part of its LNG vessel fleet with ammonia-compatible tanks. The fact that industry leaders are investing in dual-fuel capabilities shows confidence in a decarbonisation trajectory, even if they are retaining fossil fuel functionality amid uncertainty.
Biofuels are also considered an option. They require minimal retrofitting of ships, but they remain controversial for competing with food production in use of agricultural land, which can cause relative food scarcity and raise food prices. Biofuel production can also drive deforestation or peatland drainage. To be truly sustainable, biofuels would need to be produced only from waste and residues, such as used cooking oil and crop residues, but these have limited supply. As such, biofuels currently are at best a transitional solution.
Green hydrogen beyond shipping
Shipping is not the only potential user of green hydrogen and its derivatives. Green ammonia can be used in fertiliser production, which would be a key benefit for Africa. Fertiliser use in Africa is around 22kg/hectare, seven times less than the global average. African farmers desperately need more fertiliser to improve their yields, but they cannot afford to pay the premium green ammonia still entails. If production costs fall, and green fertilisers are manufactured domestically, African countries can markedly reduce their fertiliser imports and associated foreign currency spending.
Green ammonia can also be converted back into green hydrogen, which can then replace natural gas. This could help Europe decarbonise and diversify its energy sector while reducing dependence on Russian fossil fuels. Green methanol has wide industrial uses, from blending and substituting diesel to being a precursor for various chemicals.
Currently, production of fertilisers and many petrochemicals contribute around 5% of global emissions. Switching to green hydrogen would decarbonise the manufacture of these common products.
NZF: Challenges and opportunities for Africa
NZF adoption would pose both challenges and opportunities for African countries. On the one hand, maritime decarbonisation will raise certain costs for African shipping and trade sectors under any framework. On the other hand, rising demand for low-emission fuels creates a potential growth market, and African countries are well placed to competitively produce green hydrogen and its derivatives.
Challenges
African shipping ownership is negligible, accounting for less than 1% of global tonnage. African-owned vessels also tend to be among the oldest in the world, reflecting poor access to traditional ship finance and modern technologies. Transition costs for these few owners will be considerable because of the extent of catching up they will need to do. Targeted support, such as that offered by the Net-Zero Fund, will be particularly valuable here.
African seafarers generally depend on training and employment with international companies, as African fleets are too small to absorb all cadets from the continent. However, competition for these roles is high and many African cadets struggle to secure these opportunities. As the industry decarbonises, they risk being further excluded unless they garner enough experience with new fuels and technologies.[14] The African shipping industry needs partnerships that help transition their people and not just their fuels.
Decarbonisation will significantly increase trade costs for Africa. African countries already face some of the highest trade costs globally due to long distance to key markets and heavy reliance on maritime transport, which accounts for over 90% of its external trade. Greater distance results in higher emissions and, under decarbonisation schemes, higher compliance costs. Shifting to more sustainable but more costly fuels will increase freight costs, lowering export competitiveness and raising prices of imports such as food—including in contexts where food security is already fragile.
However, these issues cannot be avoided by rejecting the NZF. Alternative national and regional maritime emissions pricing frameworks would impose similar, potentially higher costs, particularly if multiple regimes result in duplication.
Opportunities
Several African countries are ideally positioned to become globally competitive producers of green hydrogen and its derivatives, particularly if the NZF creates sustained demand.
Egypt, Kenya, Mauritania, Morocco, Namibia and South Africa already have nascent green hydrogen sectors, supportable by notable renewable energy resources. Solar, wind and geothermal resources are abundant, and efficient generation of renewable energy translates directly into lower green hydrogen costs over time. Most possess major ports that can bunker ocean-going vessels (Mauritania’s ports have more limited bunkering capacity).
For example, with solar energy projects, Namibia has the potential to generate around double the amount of electricity annually than comparable installations in central Europe. The country also has high wind energy potential, thanks to its strong and consistent coastal winds in the south. Meanwhile, Kenya is looking to use its extensive geothermal resources for production of green hydrogen and derivates—for example, a Chinese-backed green fertiliser project is already gaining ground in the Rift Valley.
With NZF adoption, large African ports such as Mombasa and Durban could serve as refuelling stations, or African countries could produce green ammonia or methanol and ship to major global refuelling ports.[15] The transition could support African coastal nations in modernising their ports and related infrastructure while strengthening related industrial clusters connected. But realising this potential will depend in large part on support provided under any adopted maritime decarbonisation framework, such as the Net-Zero Fund.
Constraints and criticisms
Green hydrogen projects are not without criticism in African countries. Water availability is a primary concern, particularly in arid regions where many nascent projects are located. Large-scale green hydrogen production requires significant volumes of potable water. Although green hydrogen uses the same or less water than grey hydrogen, and careful project design can lower water requirements further, production will likely require desalination plants—and, although African countries with burgeoning green hydrogen industries have desalination plants, most are relatively small. Large desalination plants are costly, so investments will depend on green hydrogen demand certainty.
Namibia offers a useful example. The Erongo Desalination Plant, originally constructed by French uranium miner Orano to serve its Trekkopje mine, was repurposed to produce clean and reliable drinking water for local communities.[16] After an expansion, the plant now serves the entire Erongo region, producing 17.6 million cubic metres of potable water in 2025. A second desalination plant is now planned. It will be constructed by Swakop Uranium, a subsidiary of China General Nuclear Power Group, to supply water to the Husab uranium mine and nearby communities in the Erongo region.
Another recurring criticism of green hydrogen projects in Africa is that they do not create many jobs and, being export oriented, do not necessarily help expand energy access domestically (in some instances, such as the planned Hyphen Hydrogen Energy project in Namibia, a share of the renewable energy generated as part of these projects is planned to power local electrification or feed into the national grid). However, these characteristics are not unique to green hydrogen. The same criticism applies to oil and gas projects. And when it comes to jobs, even utility-scale renewable energy projects only create several hundred permanent posts. Green hydrogen projects are not a panacea, but they can still deliver value by raising tax revenues for government, increasing foreign currency earnings and spurring demand for local goods and services, while acting as a foundation to develop related industries.
Recommendations
There are key actions needed on both the African and European sides to make NZF adoption a reality. While there is scope to address legitimate concerns with the current text, extreme care should be taken to ensure that the NZF has teeth. Submission to oil-producer interests is not a strategic trade-off to attain majority support for a global framework.
African side
The IMO is a forum where each country’s vote carries equal weight. By number, African countries hold enough votes to significantly swing the outcome if they act collectively. It is the responsibility of African members to cast their votes free of influence, asserting their voice in maritime governance rather than submitting to the interests of more powerful countries. Although African countries have differing interests, African states should aim to coordinate a common position. Achieving this will likely require negotiation on a narrow set of issues, notably the pace of decarbonisation envisioned under NZF and ensuring mitigation support to developing countries.
Constructive thinking on how African concerns could be reflected in the guidelines, without reopening the NZF text itself, is vital. African countries concerned about the impact of higher trade costs on food security could put forward their own proposals to the IMO, or support others that address these concerns. For example, they could support a recent proposal from Brazil to channel Net-Zero Fund revenues to the Global Alliance Against Hunger and Poverty to help mitigate food security risks in developing countries.
The potential upside should also be factored in. By creating a market anchor for green hydrogen, NZF adoption could open up the possibility of African countries becoming producers of green hydrogen and derivative products to serve the shipping industry and local applications, such as green fertiliser. Developing this industry in Africa could create jobs, raise foreign currency earnings and tax revenues, increase procurement of local goods and services, and catalyse the development of industrial clusters around these projects.
European side
The immediate task in front of Europeans is to address potential regulatory overlap. If NZF is adopted, it will need to be the only decarbonisation regulation governing international shipping. As long as there is uncertainty around the EU’s application of ETS and FuelEU Maritime Regulation to international shipping, countries will hesitate to vote in favour of NZF. The EU needs to give a clear commitment in this regard if it hopes to garner more support for NZF adoption.
In order to get African countries on board, Europeans need to better understand and accommodate their concerns. More importantly, they must outbid the powers pushing Africans to oppose the NZF. A better offer will include firm commitments, not just rhetoric. Strategic partnerships on green hydrogen development, such as those the EU has signed with Egypt, Mauritania and Namibia, is a first step. So is providing tangible project support, as is already happening with initiatives in several African countries under the EU’s Global Gateway.
There is clear commercial interest. European companies are already involved in a number of green hydrogen projects in Africa, from German participation in Namibia’s HyIron project (which produces green direct reduced iron, or DRI, a low-carbon iron made by using hydrogen instead of fossil fuels) to TotalEnergies’ involvement in the planned Chbika green ammonia project in Morocco. Supporting European private investment in the sector (financing, de-risking instruments, technical assistance or policy dialogue under Global Gateway) would deliver win-win benefits for both European and African actors.
Importantly, Europe’s collaboration with African countries must go beyond green fuel production to include support for Africa’s maritime sector: investment in its seafarers, shipowners and infrastructure. Seatime placements, which are needed for trainee cadets to qualify, and training African seafarers for international employment in a decarbonising industry would be practical contributions to help ensure that Africa is not left behind in the transition.
The NZF may be the market catalyst needed to boost green hydrogen development—and the value of a competitive green hydrogen sector for Europe extends far beyond shipping. It offers a critical route to diversify and decarbonise its energy sector, strengthening its security and industrial competitiveness.
Now or never
The October 2025 decision to postpone the vote on NZF adoption was a major setback. As Fortescue, the Australian mining and green hydrogen company, described it, the postponement was “A lost opportunity for the world to take collective, decisive action on one of the hardest-to-abate sectors.” However, the opportunity has been delayed, not yet lost.
The postponement has prolonged the uncertainty faced by both shipowners and green hydrogen developers. Some shipowners will invest in ships capable of using low-emission fuels regardless, but most will wait.[17] NZF proponents need to reinvigorate momentum ahead of the vote in December 2026. “If NZF is killed, it’s not something you can just come back to in the future”, one close observer of the process stated. “It’s a once-in-a-generation opportunity.”[18]
A globally uniform framework led by the IMO remains the only way to create a stable demand signal for low-emission fuel development, as well as a predictable revenue stream for the Net-Zero Fund. Failing to adopt the NZF—or even weakening its current text—risks pushing large-scale low-emission fuels availability into the 2040s. Maritime decarbonisation will still happen, but more slowly and unevenly. Those most in need of support, including many African countries, will be left furthest behind.
About the author
Sarah Logan is a visiting fellow in the Africa programme at the European Council on Foreign Relations. Her main research interests are in energy and investment in Africa, with a focus on more fragile settings. She is an economist and lawyer with significant experience working with governments of countries experiencing fragility and conflict.
Acknowledgments
The author would like to thank the interviewees who shared their time and expertise in discussions for this paper. Thanks also to ECFR colleagues for their feedback and insights—Nina Schmelzer of the DARE* project, and Alex Vines and Maddalena Procopio of the Africa programme. A huge thank you to the editorial team for their support in bringing this paper to life—invaluable editing support from Taisa Sganzerla and graphics support from Nastassia Zenovich and Chris Eichberger. All errors are those of the author.

[1] Interview with an African environment and climate expert advising an African IMO delegation, online, March 3rd 2026; interview with a representative of a green hydrogen non-profit organisation, phone call, February 18th 2026.
[2] Interview with an African trade and maritime expert, online, February 27th 2026.
[3] Interview with an African environment and climate expert advising an African IMO delegation, online, March 3rd 2026.
[4] Interview with a European green-hydrogen adviser, phone call, November 14th 2025.
[5] Interview with a representative of a green-hydrogen organisation, phone call, February 18th 2026.
[6] Interview with an African trade and maritime expert, online, February 27th 2026.
[7] Interview with an African trade and maritime expert, online, February 27th 2026.
[8] Interview with an African trade and maritime expert, online, February 27th 2026.
[9] Interview with an African trade and maritime expert, online, February 27th 2026; interview with an African environment and climate expert advising an African IMO delegation, online, March 3rd 2026.
[10] Interview with an African trade and maritime expert, online, February 27th 2026.
[11] Interview with a representative of a green-hydrogen organisation, phone call, February 18th 2026.
[12] Interview with a European innovation and green-hydrogen expert, phone call, November 20th 2025.
[13] Interview with a European innovation and green hydrogen expert, phone call, November 20th 2025.
[14] Interview with an African trade and maritime expert, online, February 27th 2026.
[15] Interview with a representative of a green-hydrogen organisation, phone call, February 18th 2026; interview with a European diplomat, November 20th 2025.
[16] Interview with a representative of a uranium mining company, Swakopmund, Namibia, April 30th 2026.
[17] Interview with a European green-hydrogen adviser, phone call, November 14th 2025.
[18] Interview with a representative of a green-hydrogen organisation, phone call, February 18th 2026.
The European Council on Foreign Relations does not take collective positions. ECFR publications only represent the views of their individual authors.