Power couple: How South Korea fits in Europe’s battery strategy
Europe’s battery dependence on China is clear, but closing the gap alone will be difficult. Partnering with South Korea, the world’s second-largest manufacturer, offers a faster and more realistic route

Batteries sit at the heart of the EU’s push to decarbonise transport and energy, making them indispensable to the bloc’s 2050 net-zero target. Global demand for electric vehicle (EV) batteries alone is rising fast, with the EU set to become the world’s second largest market this decade, trailing only behind China. Add the growing demand for energy storage systems and secure access to batteries (and precursor materials) has become a key strategic priority.
Yet Europe is still highly dependent on foreign players. China dominates the entire battery supply chain, producing 80% of global battery cells, most of them within its own borders. For lithium-iron-phosphate (LFP) batteries, increasingly preferred by carmakers, China controls a staggering 94% of global production. European EVs using LFP batteries rose from 3% in 2022 to 10% in 2024, with nearly all supplied by China.
Closing the gap with a purely domestic strategy will be difficult. A more realistic route for Europe lies in deepening industrial cooperation with other countries. South Korea is one such promising partner, with globally competitive firms, large-scale manufacturing capacity, existing industrial footprint in Europe—accounting for 78% of our installed battery-manufacturing capacity—and active efforts to reduce dependencies on China.
This should be seen as a complement, not a substitute for building up Europe’s own industry. With the right policy framework, cooperation can accelerate de-risking while enabling the sharing of technology and manufacturing knowledge that many European players still lack.
The China bottleneck
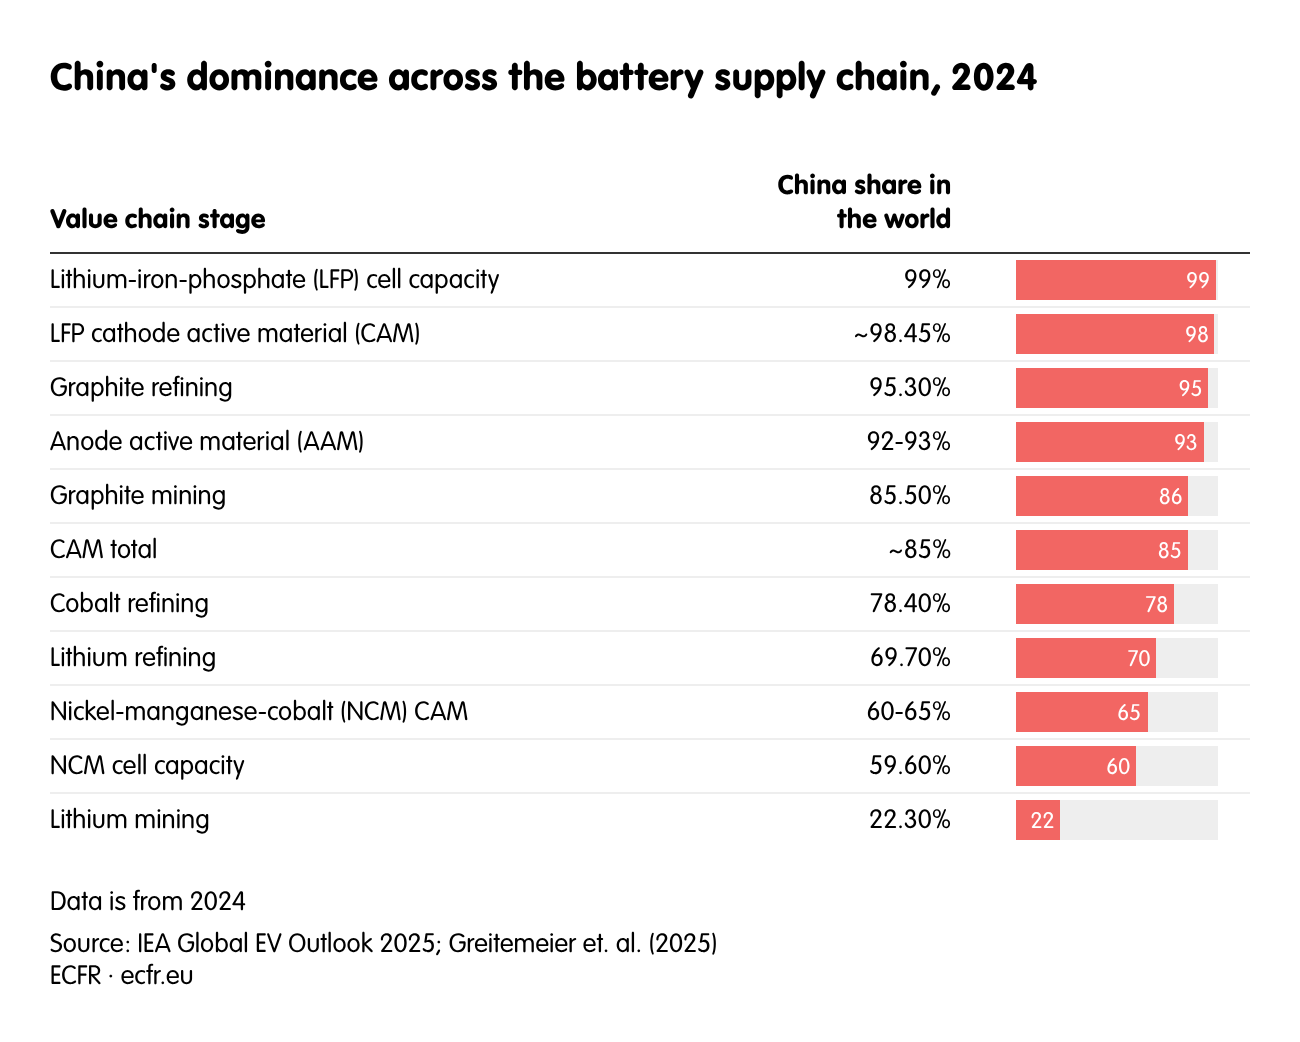
China’s dominance of the battery supply chain includes manufacturing almost 85% of cathode active materials and over 90% of anode active material, which are crucial battery components. China also leads in the refining of raw materials needed for these inputs, commanding 65% of lithium, 75% of cobalt and over 90% of graphite refining worldwide.
For Europe, this level of concentration does more than just limit its share of a fast-growing industry: it also creates a key pressure point for Beijing to coerce Europe economically. China’s October 2025 export controls on next-generation LFP technology, cathode precursors, anode active materials and battery manufacturing equipment make clear that Beijing is willing to weaponise this dominance.
Enter South Korea
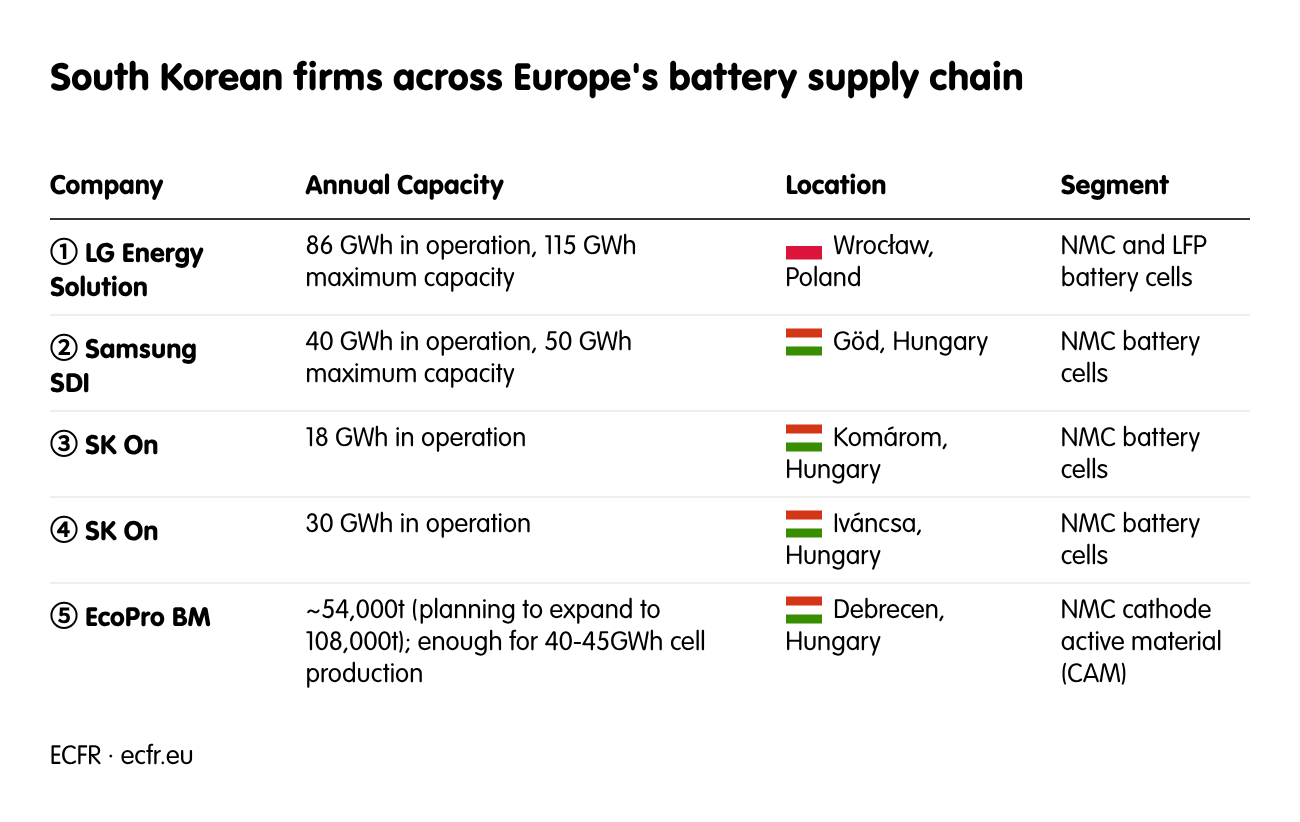
South Korea’s three leading battery manufacturers—LG Chem, Samsung SDI and SK On— hold a combined global market share of 20%, making the country the second-largest global battery manufacturer, only behind China. In Europe, Korean firms represent 78% of installed battery-manufacturing capacity, followed by European firms (13%) and Chinese firms (8%).
Despite this strong European footprint, Korean firms have been steadily losing market share in EV batteries in recent years, dropping from 78% in 2022 to only around 30% in 2025. Over the same period, China increased their share from 22% to 60%. This shift is driven by the rising popularity of the more affordable LFP batteries, whose production China controls almost alone. Korean manufacturers have historically specialised in the more energy-dense but costly nickel-manganese-cobalt (NMC) chemistry and are only beginning to move into LFP. LG Energy Solution’s plant in Wrocław, Europe’s largest battery factory, started shipping LFP cells for energy storage systems this year.

Batteries of any type can be imported into the EU at a tariff rate of just 1.3%, allowing cheaper Chinese products to undercut local manufacturers
Chinese battery makers are also building up local production in Europe: CATL is bringing 40GWh of NMC capacity online in Hungary this year and constructing a 50GWh LFP plant in Spain in a joint venture with Stellantis. Adding to the pressure is the fact that batteries of any type can be imported into the EU at a tariff rate of just 1.3%, allowing cheaper Chinese products undercut local manufacturers. Coupled with a weaker than expected EV battery demand overall, Korean plants in Europe currently run only at roughly 50% of total capacity.
Like their European counterparts, Korean battery firms face high supply chain dependencies on China. However, they have recently begun taking steps to reduce their exposure. Besides heavily investing in mining and refining partnerships with third countries, Korea is also home to several firms capable of producing cathodes, anodes and their precursors—POSCO Future M, EcoPro BM, LG Chem and L&F—with new domestic plants designed to reduce or eliminate reliance on Chinese materials.
Much of these new investments have been largely driven by regulatory pressure from the US. The Inflation Reduction Act (IRA), followed more recently by the Foreign Entity of Concern (FEOC) rules, restricts tax credits for products containing a significant share of Chinese content. Korean firms were willing to incur higher costs to comply under the expectation of future profits in a protected US market, where Chinese batteries would face tariffs of up to 175%. However, this has become less certain since the US Supreme Court struck down US president Donald Trump’s IEPA tariffs.

Building a compelling case for Korea
Amid uncertainty in the US market—where demand for EVs is stagnating or even shrinking—Europe can use its projected battery demand (up to 1.3TWh by 20230) to attract more investments from Korean firms, both on the cell level and further along the supply chain.
For this to work, Europe needs to proactively create a business case for Korea to produce China-free or -reduced battery precursors. Fortunately, many Korean firms are already doing this. Then, the EU needs a policy environment that gives Korean operators a commercial reason to route their nascent de-risked supply chains through Europe, or scale up their production already established here. For this, Europe needs to boost demand for non-Chinese battery cells and components as well as help close the price gap with Chinese competitors.
The Industrial Accelerator Act (IAA), which the European Commission has recently unveiled, is a step in this direction. It introduces “Union origin” requirements in public procurement and subsidy schemes, such as purchase credits. Six months after the IAA enters into force, EV batteries must contain at least three main specific components, including the battery cell, originating in the EU to count as “Union origin”. After the third year, these requirements increase to five components, including the cathode active material (CAM). Given that government-supported fleet purchases make up a large portion of newly registered EVs in the EU, this measure could significantly boost demand for batteries and components.
South Korea is poised to benefit. Because of its free-trade agreement with the EU, battery cells and materials made in South Korea would count as “Union-origin equivalent”, unlike Chinese ones. This creates an incentive for South Korean firms to scale up production for CAM, AAM and related materials to supply Korean battery makers both in Korea and Europe, while preparing for the stricter rules three years later. Any increase in global supply of non-Chinese battery materials that is routed to Europe strengthens Europe’s resilience.
However, the current version of the IAA also carries a risk. Because batteries produced in South Korea or another EU free-trade partner already qualify, firms may opt to simply increase production domestically and not move it to Europe. This limits positive employment effects, local value-add, deeper integration into supply chains as well as technology and knowledge transfer to European firms (crucial to develop Europe’s own battery firms). Being import-dependent on a trusted partner still hinges on that partner’s willingness and ability to prioritise EU customers over domestic, US and other demand.
That said, the significant Korean battery investments over the last eight years took place in the absence of any large EU-level policy incentives, drawn by the scale of Europe’s automotive industry and the prospective lucrative EV battery market. To strengthen these pull factors, European policy should continue efforts to reduce red tape, simplify permitting procedures and, most importantly, stay on course with the green transition. Policy reversals, like the recent softening of fleet requirements for European carmakers, undermine confidence in Europe’s future battery demand and ultimately weaken Europe’s attractiveness as an investment destination.
China’s battery dominance in Europe is not inevitable. South Korea already stands as a capable and established partner, producing NMC and increasingly LFP cells for both EVs and energy storage, while actively diversifying their supply chains from Chinese inputs. With the right policy framework, this partnership could form the backbone of a more resilient battery supply chain in Europe.
The European Council on Foreign Relations does not take collective positions. ECFR publications only represent the views of their individual authors.